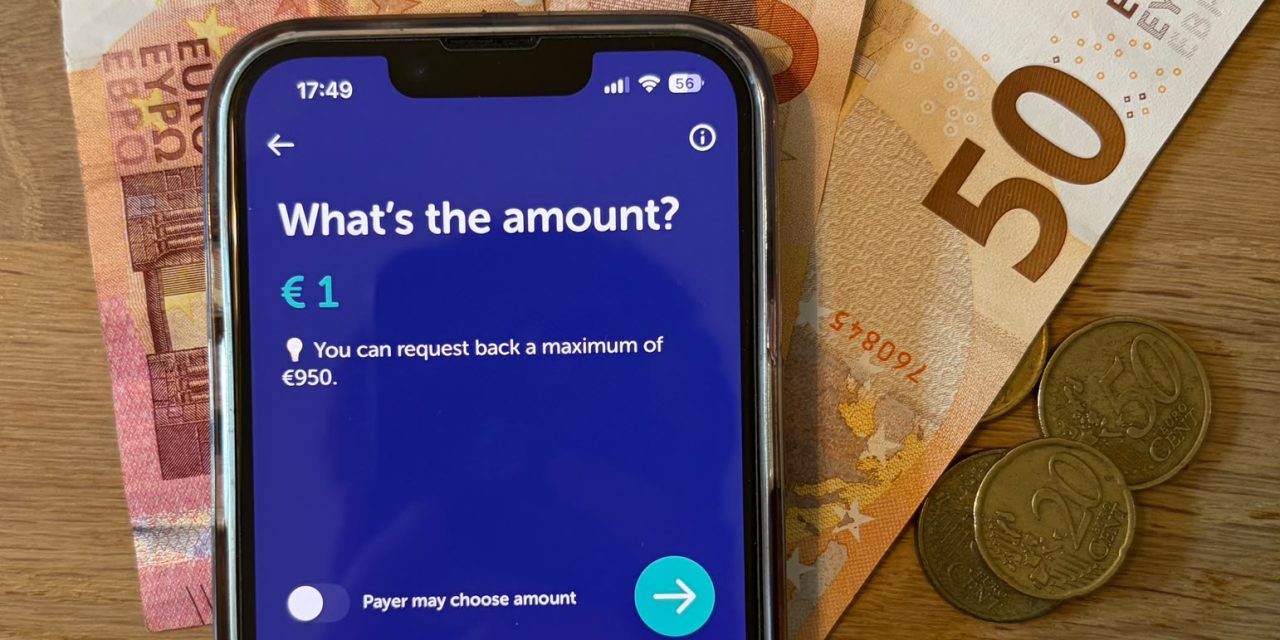
‘Going Dutch’ is one of the most well-known expressions associated with the Netherlands. The term, stemming as far back to the Anglo-Dutch War in the 17th century, relates to the fact that it is normal to split the bill rather than one person picks up the tab. It’s a small expression of a much broader reputation for financial discipline. With the ever more popular usage of the ‘Tikkie culture’, the app that brings going Dutch to the 21st century, does this stereotype still hold?
‘The Dutch have a very specific relationship with money,’ says Antoine Vonk, CEO of ING Belgium, who also points out that this relationship doesn’t necessarily mean that the Dutch are stingy. ‘It’s not about thrift. It is about modesty, self-reliance, prudence and a strong dislike of financial excess. Compared with other European cultures, Vonk sees the Netherlands between two different financial cultures. On the one side you have the more individualistic financial culture of Anglo-Saxon countries and the more family-driven approach more associated with southern Europe. ‘Attitudes towards money are rooted in history.’
For the Netherlands this means the Reformation and subsequent Calvinism and the Second World War after which the lesson was learned that’s it’s good to have a little extra to save.’ There is also a more current element: ‘In a small, densely populated country, making sensible choices has traditionally been important’. That attitude remains visible in household finances today. According to the bank ABM Ambro only 34 percent of people use consumer credit or personal loans and on a national scale the Dutch debt to GDP ratio is sitting around 44% which is well below the EU average of 83%. ‘Dutch people save a lot, while at the same leveraging with lending,’ Vonk says. ‘The Dutch borrow to invest, not to consume.’
Financial caution in the Netherlands does not necessarily mean avoiding debt. Instead, it is often about using, and borrowing, money in a purposeful way. For Households, a practical exercise: What comes in, what goes out and what can be saved.
large supermarkets play in to the hands of the consumer mentality of saving
But this mentality can also be cause for concern: Vonk alludes to the facts that households and institutions, particularly through pension funds have too much saved ‘The concern is that excessive caution can reduce risk taking and investment, potentially limiting economic opportunities in the country.’
The same cultural differences are also seen at European level. The Greek debt crisis, debates over collective European borrowing and disagreements between northern and southern European countries over public finances have exposed fundamentally different attitudes towards saving, debt and spending.
The stereotype has to be seen in wider context. The Dutch are not unwilling to spend. Rather they tend to want financial stability and control before they do so. In an economy built on investment, pensions and access to credit, being stingy is no longer the best description. It may be more accurate to say that the Dutch are a fan of money with a plan.
Even small change goes a long way in a Dutch household